Your Paid-Off House Can't Pay the Grocery Bill in Retirement
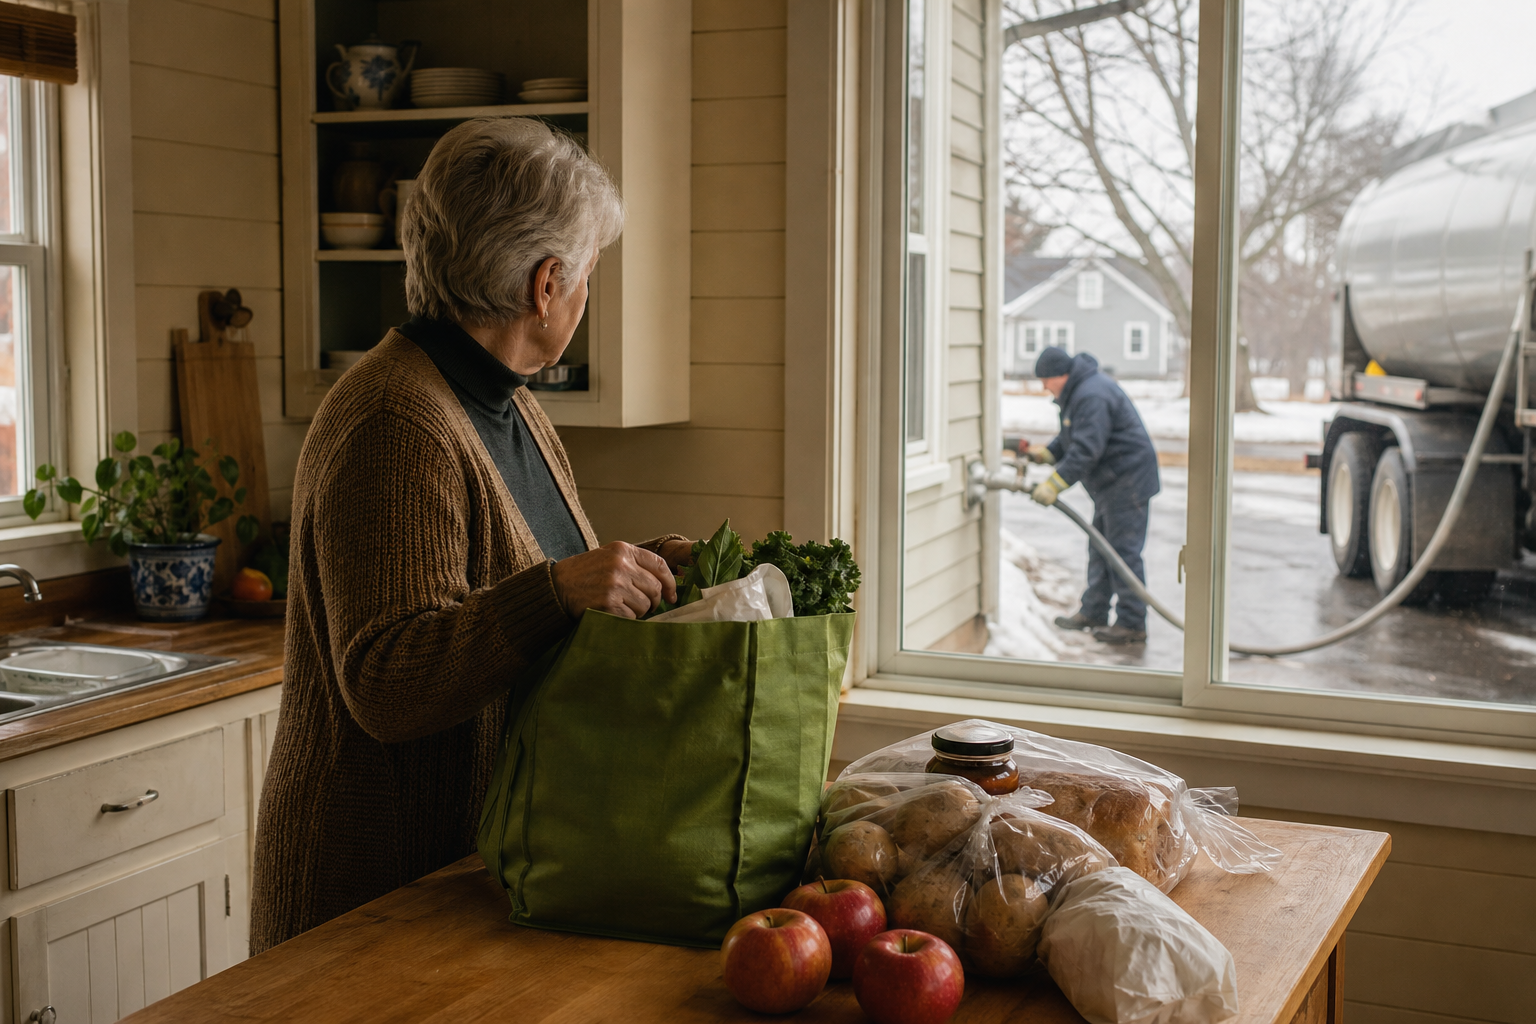
A home in Charlottetown can be paid off in full, worth a comfortable sum on paper, and still leave its owners nervous every time the heating oil truck pulls into the driveway. Property tax, insurance, a furnace that needs replacing, groceries that cost more each spring: none of these care what the house would sell for. By the end of this piece, you'll know how to check whether your retirement plan can cover those ordinary bills without forcing you to sell the house or borrow against it when money gets tight.
If you've ever made an extra mortgage payment, then looked at what was left for retirement savings and wondered whether you were actually getting ahead, this is the gap worth checking. The choice you make with your next spare dollar, mortgage or savings, decides how much room you'll have to move at 70. Paying down the house feels responsible, and it is. Sending nearly every spare dollar there can still leave you owning something valuable while the monthly budget refuses to balance.
What a paid-off home covers in retirement, and what it leaves on your plate
Clearing the mortgage removes your largest housing payment. That's a real gain, and it lowers the income you'll need. The house keeps billing you after that, though. On the Island, a mortgage-free owner still pays municipal and provincial property tax, home insurance, heating through a long winter, and the steady drip of maintenance: a roof, a well pump, a deck that needs rebuilding. Those costs come out of income, and the equity in the walls can't touch them.
Home equity generally becomes spendable in one of two ways, and both have a price. Selling means you need somewhere else to live, plus real estate commissions, legal fees and moving costs, and the gap between a family home and a smaller place may be narrower than you'd hoped. Borrowing, through a line of credit or a reverse mortgage, brings interest, eligibility requirements and loan terms you'll live with for years. Approval isn't automatic because the equity is there.
So the question for your plan today is simple: does it work if you stay in the house and never borrow against it?
How to test your retirement plan without spending the house
Start by putting two numbers side by side. The first is your dependable after-tax income in retirement: government benefits, any workplace pension, and the withdrawals you expect from savings. Remember that RRSP and RRIF withdrawals are taxed as income, while TFSA withdrawals aren't. The second is your everyday spending, including the full cost of running a mortgage-free home.
Here's an illustrative example. If your household spends $5,000 a month and dependable after-tax income comes to $4,200, the shortfall is $800 a month, or $9,600 a year. If the only way to close that gap is the house, then your plan already assumes selling or borrowing, and that decision deserves to be made openly now rather than discovered in a hard winter.
This is where your working years matter most. Home equity is valuable, but a retirement plan also needs money you can spend without selling your home or taking on debt. Building that money means weighing extra mortgage payments against TFSA and RRSP contributions. The right balance depends on your mortgage rate, your tax bracket, your contribution room and how much flexibility your family needs. Keep three questions separate as you decide: how easily you can reach the money, how much the investments might rise or fall, and how each dollar is taxed on the way out. A TFSA is easy to withdraw from, but what's inside it can still lose value.
Being mortgage-free and having a retirement budget that works are two separate achievements, and you want both. The house can stay what it should be in retirement: a place of security, kept in reserve rather than drawn on as the emergency fund. A good first move is to ask for a retirement cash-flow projection that assumes you stay in your home and take on no new borrowing. If it shows a gap, coordinated financial and mortgage advice can help you decide where your next dollar does the most good. If it shows no gap, you'll know the house is yours to enjoy.


A home in Charlottetown can be paid off in full, worth a comfortable sum on paper, and still leave its owners nervous every time the heating oil truck pulls into the driveway. Property tax, insurance, a furnace that needs replacing, groceries that cost more each spring: none of these care what the house would sell for. By the end of this piece, you'll know how to check whether your retirement plan can cover those ordinary bills without forcing you to sell the house or borrow against it when money gets tight.
If you've ever made an extra mortgage payment, then looked at what was left for retirement savings and wondered whether you were actually getting ahead, this is the gap worth checking. The choice you make with your next spare dollar, mortgage or savings, decides how much room you'll have to move at 70. Paying down the house feels responsible, and it is. Sending nearly every spare dollar there can still leave you owning something valuable while the monthly budget refuses to balance.
What a paid-off home covers in retirement, and what it leaves on your plate
Clearing the mortgage removes your largest housing payment. That's a real gain, and it lowers the income you'll need. The house keeps billing you after that, though. On the Island, a mortgage-free owner still pays municipal and provincial property tax, home insurance, heating through a long winter, and the steady drip of maintenance: a roof, a well pump, a deck that needs rebuilding. Those costs come out of income, and the equity in the walls can't touch them.
Home equity generally becomes spendable in one of two ways, and both have a price. Selling means you need somewhere else to live, plus real estate commissions, legal fees and moving costs, and the gap between a family home and a smaller place may be narrower than you'd hoped. Borrowing, through a line of credit or a reverse mortgage, brings interest, eligibility requirements and loan terms you'll live with for years. Approval isn't automatic because the equity is there.
So the question for your plan today is simple: does it work if you stay in the house and never borrow against it?
How to test your retirement plan without spending the house
Start by putting two numbers side by side. The first is your dependable after-tax income in retirement: government benefits, any workplace pension, and the withdrawals you expect from savings. Remember that RRSP and RRIF withdrawals are taxed as income, while TFSA withdrawals aren't. The second is your everyday spending, including the full cost of running a mortgage-free home.
Here's an illustrative example. If your household spends $5,000 a month and dependable after-tax income comes to $4,200, the shortfall is $800 a month, or $9,600 a year. If the only way to close that gap is the house, then your plan already assumes selling or borrowing, and that decision deserves to be made openly now rather than discovered in a hard winter.
This is where your working years matter most. Home equity is valuable, but a retirement plan also needs money you can spend without selling your home or taking on debt. Building that money means weighing extra mortgage payments against TFSA and RRSP contributions. The right balance depends on your mortgage rate, your tax bracket, your contribution room and how much flexibility your family needs. Keep three questions separate as you decide: how easily you can reach the money, how much the investments might rise or fall, and how each dollar is taxed on the way out. A TFSA is easy to withdraw from, but what's inside it can still lose value.
Being mortgage-free and having a retirement budget that works are two separate achievements, and you want both. The house can stay what it should be in retirement: a place of security, kept in reserve rather than drawn on as the emergency fund. A good first move is to ask for a retirement cash-flow projection that assumes you stay in your home and take on no new borrowing. If it shows a gap, coordinated financial and mortgage advice can help you decide where your next dollar does the most good. If it shows no gap, you'll know the house is yours to enjoy.
Read Next
Lump-Sum Inheritance or a Testamentary Trust? Here's Who Each One Is For
A $2,000 Storm Bill Is the Liquidity Test Most Canadians Are Failing
Capital Gains Are the Wrong Scoreboard When Your Income Can Vanish
If Your Slow Months Need a Credit Card, Your Good Months Aren't Good Enough